
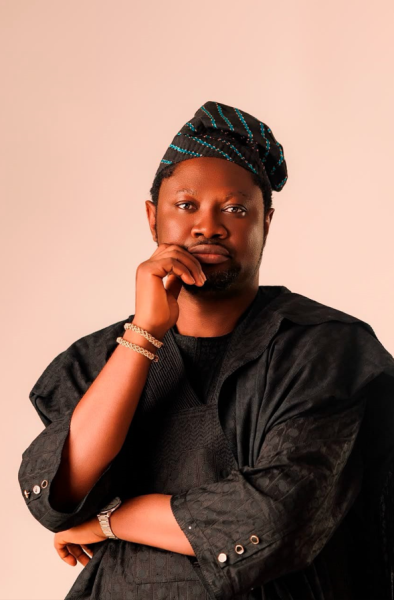
By Hon. (Dr.) Saheed Mosadoluwa Audullahi
Executive Managing Director/Chief Executive Officer, Harmony Garden & Estate Development Ltd.
Nigeria, 29th Sep 2026—Homeownership remains one of the strongest aspirations of the Nigerian family. Yet for millions of Nigerians, the dream of owning a home remains difficult to achieve, not necessarily because of a lack of income or willingness to pay, but because conventional housing finance structures often require financial commitments that do not reflect the realities of the average Nigerian.
The question we must therefore ask is not simply, “How do we build more houses?” It is also, “How do we make homeownership financially accessible?”
Nigeria’s housing challenge requires a fundamental rethink of how people finance property.
Beyond the Traditional Mortgage Model
The traditional mortgage model can be difficult for many Nigerians because it often depends on substantial upfront payments, formal income structures, long-term credit assessment, and repayment conditions that may not accommodate entrepreneurs, informal-sector workers, young professionals, or Nigerians living in the diaspora.
This does not mean conventional mortgages are irrelevant. Rather, it means Nigeria needs more financing options.
Homeownership should have multiple pathways: conventional mortgages, rent-to-own structures, structured installment payments, cooperative financing, and other innovative models that allow people to acquire property according to their financial capacity.
The objective should be to create a system where ability to pay over time can be as important as the ability to pay everything at once.
From Renting to Owning
For many Nigerians, rent consumes a significant portion of household income without creating an ownership asset.
This is where rent-to-own models can provide an alternative pathway.
At Harmony Garden & Estate Development Ltd., this thinking informed the development of the Ibile Traditional Mortgage System, a structured approach designed to make property acquisition more progressive and accessible.
Under the model, a buyer can begin with a 10% entry commitment, receive allocation at 30%, move into the property at 50%, and spread the remaining balance over up to five years at a single-digit annual rate of 7.5% – 9.9%, according to the current programme structure.
The principle is straightforward: homeownership should be a journey that people can enter progressively, rather than an opportunity reserved only for those who can afford the full cost immediately.
This approach is particularly relevant to a country where income patterns are diverse and where many people have the capacity to meet structured obligations but struggle with large upfront payments.
Financing Must Reflect Different Nigerians
There is no single Nigerian homeowner.
There is the young professional buying a first property, the entrepreneur with fluctuating income, the family seeking a permanent residence, the investor acquiring land for future development, and the Nigerian in the diaspora looking to establish a home in the country.
Each may require a different financing structure.
That is why the future of Nigerian housing finance must be built around flexibility, transparency, and choice.
Financial institutions and developers should work together to create products that consider:
● Repayment capacity rather than only upfront capital;
● Different income structures;
● Longer and realistic repayment periods;
● Diaspora participation;
● Rent-to-own arrangements;
● Structured installment payments;
● Clear documentation and property titles; and
● Transparent pricing.
Innovation, however, must never mean compromising accountability. Every financing model must clearly communicate the total cost, payment obligations, documentation, allocation conditions, and applicable charges.
The Developer’s Responsibility
The responsibility for solving Nigeria’s housing challenge cannot rest entirely with government or financial institutions.
Developers also have a significant role to play.
The modern real estate developer must think beyond putting buildings or plots on the market. The developer must consider how the customer will access, finance, and ultimately own the property.
This philosophy is reflected in Harmony Garden’s Seven Citadels of Joy, Ogba-Idunnu, comprising GranVille Estate, Lekki Aviation Town, Majestic Bay Estate, The Parliament Estate, Oju-Alaro GRA, HarmonyCasa Estate, and HarmonyVille Estate. The company currently documents more than 4,600 hectares of acquired land assets across Lagos State.
The estates offer different locations, titles, plot sizes, and payment structures, creating opportunities across different property needs and financial capacities.
For example, current development documentation includes HarmonyCasa Phase II residential plots beginning from ₦15 million, while The Parliament Phase II offers 300sqm residential plots from ₦16.5 million, subject to the stated terms and applicable conditions.
The wider lesson is that affordability must be considered from the beginning of the property-development process.
Affordability Is More Than the Price of Land
Reducing the selling price of land alone will not solve Nigeria’s housing problem.
We must also address the cost of infrastructure, land administration, documentation, construction, financing, and transaction processes.
A home that is affordable to purchase but burdened by unclear documentation, excessive transaction costs, or inadequate infrastructure is not truly affordable.
This is why housing reform must be holistic.
Government, financial institutions, and developers need to work together to improve land administration, strengthen property documentation, expand mortgage access, support infrastructure development, and reduce unnecessary transaction costs.
At the same time, technology can improve property transactions through digital documentation, customer portals, virtual inspections, electronic payments, and more transparent property records.
Homeownership Is an Economic Strategy
Housing should not be viewed only as a social need. It is also an economic engine.
Property development creates employment across construction, engineering, architecture, manufacturing, transportation, finance, professional services, and facility management.
More importantly, homeownership can provide families with a long-term asset that contributes to financial stability and intergenerational wealth.
This is why my philosophy has always been:
“Empower people, develop land, build legacy.”
The objective is not simply to sell property. It is to create opportunities for Nigerians to participate in wealth creation through responsible property ownership.
The Ibile Traditional Mortgage System reflects this philosophy by creating a structured pathway from aspiration to ownership, while Harmony Garden’s estate developments provide the physical communities within which that ownership can take place. The company’s documentation positions the model as an avenue for Nigerians at home and in the diaspora to transition progressively from tenants to homeowners.
The Way Forward
Nigeria does not need one housing-finance solution. We need an ecosystem of solutions.
Government must continue strengthening housing policies, land administration, and public mortgage institutions.
Financial institutions must develop financing products that reflect the diversity of Nigerian incomes.
Developers must innovate not only in property development but also in customer financing and access.
Consumers must also become better informed about property titles, repayment obligations, documentation, and the long-term implications of their financial commitments.
The future of Nigerian homeownership must therefore be built on accessibility, transparency, flexibility, and responsible innovation.
The goal should be clear: a Nigerian should not have to choose between paying rent indefinitely and waiting until they have accumulated enough money to purchase a home outright.
There should be credible pathways between those two extremes.
That is why innovative models such as the Ibile Traditional Mortgage System matter.
If we can successfully connect land, infrastructure, financing, and responsible repayment structures, we can move Nigeria closer to a housing market where more families can transition from renting to owning, from aspiration to allocation, and from property ownership to generational legacy.
The future of Nigerian housing is not simply about building more homes. It is about building more pathways to homeownership.
Media Contact
Organization: Harmony Garden & Estate Development Ltd.
Contact Person: Kabiru Audullahi Mosadoluwa
Website: http://landbookbyharmony.com/
Email: Send Email
Country: Nigeria
Release id: 49504
The post Making Homeownership Accessible: Rethinking Nigeria’s Housing Finance System appeared first on King Newswire. This content is provided by a third-party source.. King Newswire makes no warranties or representations in connection with it. King Newswire is a press release distribution agency and does not endorse or verify the claims made in this release. If you have any complaints or copyright concerns related to this article, please contact the company listed in the ‘Media Contact’ section
Disclaimer: The views, suggestions, and opinions expressed here are the sole responsibility of the experts. No Newstribune 360 journalist was involved in the writing and production of this article.